

Retirement income planning · Idaho
When your paycheck stops,
what takes its place?
You know what lands in your bank account each payday. Let’s plan what that could look like in retirement.
Let’s talk about your retirement incomeComplimentary introductory call · Talk directly with Andrew
Let’s put them together.
Am I on track to retire?
Get a starting estimate of what you could save and what you may need for retirement.
All amounts are in today’s dollars. Use household totals for money; use one planning age consistently.
Your starting estimate
Talk through your estimate with Andrew in a complimentary introductory call.
Illustration only—not a guarantee. All amounts are in today’s dollars. Assumes steady returns and spending down savings through your selected planning age.
How this estimate works
From saving to spending
Your account balance is only part of the picture.
The next step is understanding how your money can support everyday life once you leave work.
What will cover the bills?
See how Social Security, pensions, and withdrawals from savings could come together to meet your spending needs.
Which money do you use first?
Consider how drawing from different accounts affects taxes, investments, and the money available to spend.
How do you plan for change?
Account for rising costs, market fluctuations, healthcare needs, and a retirement that could last decades.
Putting the pieces together
Build a plan for your retirement paycheck.
We look at how your income sources, investments, and withdrawals can work together to support the life you want.
Understand what you expect from Social Security, pensions, and savings—and when each source could begin.
Consider which accounts to draw from, how much you may need, and how taxes affect what you keep.
Plan for changing expenses, market conditions, and the decisions you’ll revisit along the way.
A plan that looks ahead
Your income plan needs to account for more than the next month.
Are you taking the right amount of risk?
Too much risk could leave you vulnerable when you need to draw from savings. Too little could make it harder for your money to keep up with rising costs over a long retirement.
We help you weigh investment risk against your income needs, timeline, and ability to weather losses. If those needs don’t align, we explore adjustments to the plan.
What happens to the people who depend on you?
A retirement plan should consider more than your own income. We help you review how a surviving spouse would be supported, who is named on your accounts, and how your financial plan aligns with your wishes for loved ones.
We coordinate with your estate attorney when needed to connect those decisions with your estate documents.
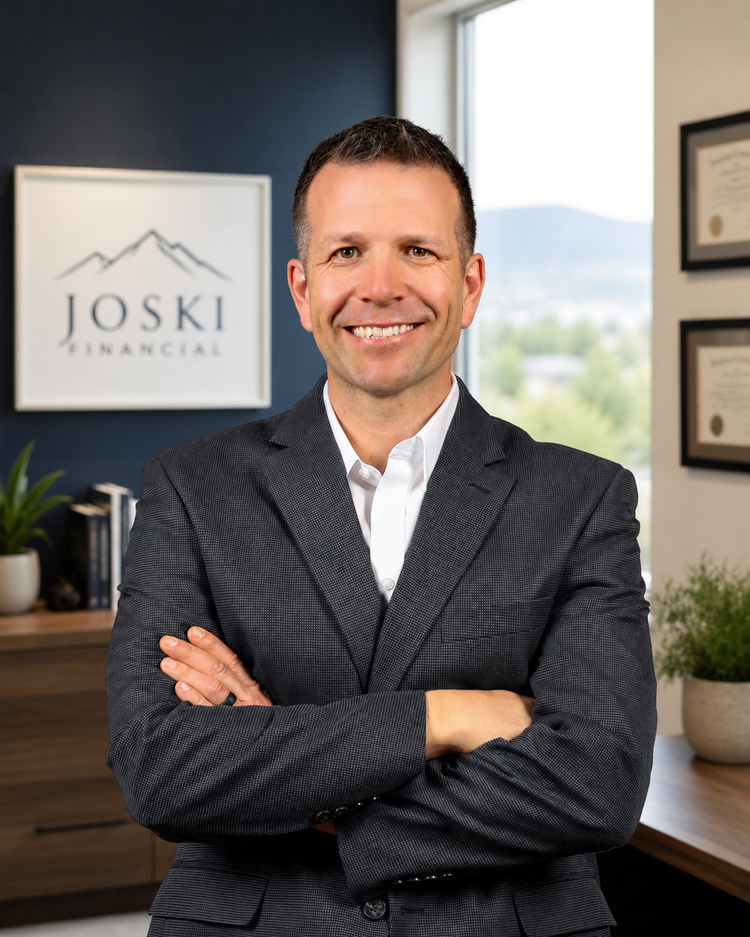
Work directly with your advisor
Andrew Joski
Founder & Independent Financial Advisor
We’ll talk through your questions, explain the options, and agree on services and fees before you decide to work together.
Explore services & fees →Before we talk
A few questions you may have.
Do I need a large investment account?
No. Joski Financial has no account minimum. We’ll discuss your needs, which services may fit, and the fees before you decide to move forward.
What happens during the complimentary call?
We’ll discuss your retirement timeline, income questions, and what you’re looking for in an advisor. The call is an introduction. Detailed analysis and a personalized plan are part of a separate engagement.
Can you help if I’m already retired?
Yes. We can discuss income sources, withdrawals, investment management, and changes that may affect your plan.
Your next step
Let’s talk about your retirement paycheck.
Start with a complimentary introductory call about your timeline, income sources, and the questions on your mind.
No documents or account balances are needed to start. No obligation to become a client.